
What happens if the buyer's financing falls through on my Medicine Hat home?
If the buyer's financing falls through after your Medicine Hat home is conditional, the sale doesn't move forward as planned, and what happens next is controlled by the financing condition and deadline in your signed offer. If the condition isn't waived by that date, the contract may become void and you may be able to consider other offers, but the exact wording and timing matter. Get the deadline, the lender's status, and any extension request in writing right away.
Key Takeaways
* A mortgage pre-approval is not confirmation of financing for your specific property, so a conditional sale is not a firm sale.
* The financing condition has an expiry date, and the precise wording of your signed offer controls what each side can do.
* An extension of the financing deadline must be agreed in writing before the original deadline expires, and you are not required to grant one.
* If the condition isn't waived by the deadline, the transaction may become void under the offer's terms, but don't assume it is either complete or cancelled without checking the contract and notices.
* Whether you can keep showing the home or accept a backup offer depends on the contract and your listing instructions, so have your listing representative review the offer first.
Why can financing fail when the buyer was already pre-approved?
Because a pre-approval is not final approval for your specific property. The Real Estate Council of Alberta (RECA) Home Buyer's Guide explains that before a buyer waives a financing condition, the lender or mortgage broker generally needs property-specific documents, such as the accepted offer, listing information, title and, where applicable, a Real Property Report.
That is the point where a pre-approval turns into a real review of your home. I walk my sellers through this early, because the gap between "accepted" and "firm" is where most of the anxiety lives.
What can go wrong at the final-approval stage?
Two things can derail approval: a change in the buyer's circumstances, or the property not supporting the loan the buyer needs.
* The buyer's situation changes. Changes in employment, income, credit, debt or other financial circumstances can affect final approval.
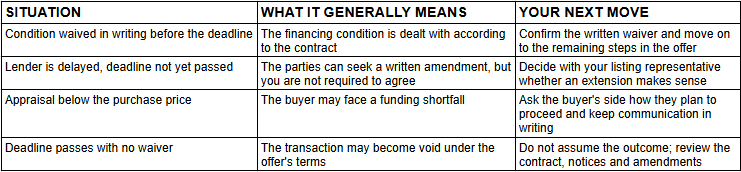
* The appraisal comes in low. A lender may require an appraisal, and a property that appraises below the purchase price can create a funding shortfall for the buyer, according to RECA's guidance on pre-approvals.
* The property type, location or value limits the terms. RECA notes these factors can affect whether, and on what terms, financing is available.
Is a conditional offer the same as a sold home?
No. A conditional offer becomes final only after the agreed conditions are satisfied or waived according to the contract, as RECA explains. Financing, inspection, condominium-document review and the sale of the buyer's existing property are common examples of conditions.
Until the financing condition is dealt with, you have an accepted offer with a question mark on it. The framework is provincial, so it works the same way whether your home is in SE Hill, Ross Glen, River Flats or Redcliff.
What should you do the moment you hear financing is in trouble?
Find the financing-condition expiry date in your signed offer and get a written status from the buyer's side. Time matters here, because your options can change the day that deadline passes.
Conditions in an Alberta offer should carry an expiry date, and the RECA Home Buyer's Guide makes clear that the buyer and seller must address the condition by that agreed date. Here is the order I work through with sellers:
1. Pull the signed Offer to Purchase and every amendment. Read the exact financing-condition wording and the stated deadline.
2. Ask the buyer's representative for the lender's status. What is the lender waiting on: documents, an appraisal, or a decision?
3. Don't treat "the mortgage is approved" as a waiver. A verbal or informal assurance is not the same as the condition being waived under the contract.
4. Look for written lender confirmation. RECA's Real Estate Act Rules identify a written lender confirmation to fund the mortgage as a relevant financing-confirmation standard. It is not a substitute for reviewing your particular offer and the lender's commitment.
5. Call your listing representative before you respond to anything. This is exactly the kind of moment where one wrong reply can narrow your options.
How the common situations break down
Should you agree to extend the financing deadline?
That's your decision, and you are not required to grant an extension. RECA's guidance on missed financing deadlines says that when a lender is delayed, the parties can seek a written amendment, but it must be agreed to before the original deadline expires.
If the delay looks like paperwork and the buyer's side is communicating clearly, a short written extension can keep a good sale alive. If the explanations keep shifting, that tells you something too. Your specific answer depends on the details of your offer, and that's where I sit down with you and weigh it.
What happens if the deadline passes?
If the financing condition isn't waived by the contractual deadline, the transaction may become void under the offer's terms, and you may be able to consider another offer, per the same RECA guidance. The effect depends on the wording of the signed contract and the timing of any amendment.
Don't assume the deal is automatically complete or automatically cancelled. The signed contract, written notices and amendments decide the result. If there's any dispute about what happened, an Alberta real estate lawyer is the right person to advise you, because consumer guidance is not a substitute for legal advice.
Can I keep showing or relist my Medicine Hat home while the offer is conditional?
It depends on the terms of your signed offer, your brokerage instructions and what has been communicated between the parties. Have your listing representative review the existing offer before you change anything about how the property is marketed.
Can I accept a backup offer?
Whether a backup offer is permitted, or sensible, comes down to the contract. I don't guess at this. I read the offer, check what the buyer's side has been told, and then we decide together whether a backup makes commercial sense for your Medicine Hat home.
What if the sale ends and I need to relist?
If the deal does end, you're back in the market with a clearer picture. If the problem was an appraisal shortfall, that is useful information about how the lender saw your price, and we talk through it before the next round. If it was the buyer's personal circumstances, the home itself may be fine and the conversation is about moving quickly.
To think through the bigger picture, my market update for Medicine Hat sellers is a good place to start, and my guide to net proceeds explains the cost categories to keep in mind if you're re-running your numbers.
FAQ
Can a buyer's mortgage be denied after the seller accepts a conditional offer in Medicine Hat?
Yes, because a pre-approval is not final approval for a specific property. The lender reviews property documents, may require an appraisal, and considers any change in the buyer's employment, income, credit or debts before final approval.
Is a mortgage pre-approval enough to remove the financing condition in Alberta?
No, a pre-approval does not confirm financing for your particular home. The financing condition is dealt with according to the wording of the signed offer, and RECA distinguishes pre-approval from property-specific financing confirmation.
Can the seller extend the financing-condition date?
Yes, but you are not required to. Any extension should be a written amendment agreed to before the original deadline expires, and I'd have your listing representative review it before you sign.
What happens if the appraisal comes in below the purchase price?
The buyer may face a funding shortfall. RECA notes that a property appraising below the purchase price can create a gap the buyer must address, so ask the buyer's side how they plan to proceed and keep that communication in writing. The details are covered in RECA's pre-approval guidance.
Can the seller accept a backup offer while the first offer is conditional?
It depends on the terms of the first offer, your brokerage instructions and the parties' communications. Have your listing representative review the existing contract before responding to any other offer.
Your next step when financing wobbles
A conditional sale isn't firm until the conditions are satisfied or waived, so your best protection is knowing your deadline, keeping everything in writing, and having someone read the contract with you. If you're selling a Medicine Hat home, or you're already under contract and nervous about the buyer's financing, schedule a consultation with my team and we'll go through your offer line by line.
About Elizabeth McNally
Elizabeth McNally is an Elite REALTOR® and team leader at Real Estate Collective in Medicine Hat, Alberta, with 20+ years of experience helping buyers, sellers, and investors. A proud member of a multi-generational Medicine Hat family, she leads a team recognized as #1 in Canada for 2023 and 2024.
Real Broker, #1 Medium Team 2025 and in 2026 #1 Small team for units sold.
Equal Housing Opportunity. Real estate professionals in Alberta are regulated by the Real Estate Council of Alberta (RECA). Listings courtesy of REAL BROKER; MLS data via Pillar 9. This article is general information, not legal, tax, or financial advice; confirm your own situation with your closing agent, tax advisor, or lender.